


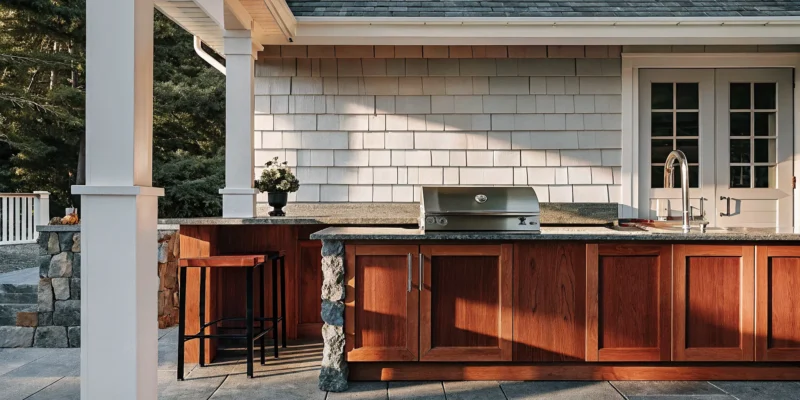
You’ve picked out the perfect spot in your backyard, you know which grill you want, and you can already picture the beautiful stone countertops. The only thing standing in your way is the budget. A complete outdoor kitchen is a major project, and the upfront cost can feel daunting. This is where financing comes in, turning a large one-time expense into a predictable monthly payment. If you’re asking, can I finance outdoor kitchens in Long Island, you’re asking the right question to make your project happen sooner. Financing can cover everything from the pavilion overhead to the plumbing and electrical work. This guide explains how it all works, so you can move forward with confidence.
Key Takeaways
- Build a Better Kitchen Sooner: Financing makes your project more accessible, allowing you to invest in high-quality materials and appliances right away instead of settling for less or waiting years to save up.
- Understand Your Financing Choices: You have several options, including plans from your contractor, home improvement loans, and home equity lines of credit; comparing them helps you find the best terms for your budget.
- Secure the Best Deal with Preparation: Know your credit score before you apply, compare the APR from multiple lenders to understand the true cost, and carefully review the loan agreement to avoid hidden fees.
Your Guide to Financing an Outdoor Kitchen on Long Island
Imagine hosting summer barbecues with friends and family, cooking delicious meals without being stuck inside. An outdoor kitchen transforms your backyard into the heart of your home, creating a perfect space for entertaining and making memories. It’s a fantastic addition to any Long Island property, extending your living area and adding significant value.
Of course, a project of this scale is a major investment. From high-quality grills and appliances to beautiful stone countertops and custom cabinetry, the costs can add up. But the price tag shouldn’t stop you from creating the backyard oasis you’ve always wanted. This is where smart financing comes in. Breaking down the cost into manageable monthly payments can make your dream project achievable right now, without needing to dip into your long-term savings.
Understanding your financing options is the first step. There are several paths available, including home improvement loans, home equity lines of credit (HELOCs), and even payment plans offered directly by your contractor. Each option has its own set of benefits, and the right choice depends on your financial situation and project scope. At Gappsi, we guide homeowners through every part of the process, from initial design and material selection to expert masonry and installation. We believe a clear financial plan is just as important as a solid foundation, and this guide will walk you through everything you need to know to get started.
What Does Outdoor Kitchen Financing Cover?
When you think about financing an outdoor kitchen, you might just picture the grill and countertops. But the great news is that financing can cover nearly every aspect of your project, from the ground up. This allows you to create a complete, fully functional, and beautiful outdoor living space without having to compromise on quality or features due to immediate budget constraints. Think of it as bundling the entire dream project into one manageable plan, making it easier to bring your vision to life all at once.
Financing covers all the essential components that turn a simple patio into a true outdoor culinary hub. This includes the foundational work, the cooking appliances you’ve been eyeing, the structures that provide comfort and shade, and all the necessary utility hookups. By financing, you can ensure every part of the project is handled professionally, creating a cohesive and high-quality space you’ll enjoy for years. You can see how these elements come together in completed Gappsi projects to get a better idea of the possibilities. Let’s break down exactly what your financing plan can include.
Appliances and Cooking Equipment
Financing makes it possible to equip your outdoor kitchen with the high-performance appliances that make cooking outside a true pleasure. You don’t have to settle for just a basic grill. Your plan can cover a wide range of equipment, including built-in gas grills, smokers, pizza ovens, and even flat-top griddles. Beyond cooking, you can include convenient features like outdoor-rated refrigerators, ice makers, wine chillers, and sinks with running water. This lets you build a complete culinary workspace, minimizing trips back inside and maximizing your time with guests. Getting the right home remodeling plan helps you install these features seamlessly.
Masonry, Stonework, and Countertops
The structure and finish of your outdoor kitchen are just as important as the appliances. Financing can cover all the materials and labor for the custom masonry that forms the base of your kitchen, as well as the beautiful countertops that provide your workspace. You can choose from a variety of durable and stylish materials, like natural stone, brick, or modern porcelain veneers. Experts in stonework can build a strong and stunning foundation that not only supports your appliances but also enhances your backyard’s aesthetic. This part of the project is a long-term investment in your property’s beauty and value, and financing helps you select the best materials without compromise.
Pavilions, Pergolas, and Shade Structures
An outdoor kitchen is much more enjoyable when it’s protected from the hot sun or a passing shower. Financing can include the design and construction of a permanent shade structure like a pavilion or pergola. These structures define your outdoor kitchen as a distinct “room” in your backyard and provide essential comfort for you and your guests. When building an outdoor kitchen, it is important to ensure adequate ventilation, and a well-designed pavilion or pergola can be engineered to provide both shelter and airflow. This addition makes your kitchen more functional across different seasons and times of day, truly extending your home’s living space.
Lighting, Plumbing, and Electrical Work
A fully functional outdoor kitchen requires the same utilities as its indoor counterpart, and financing covers these crucial installations. This includes all the necessary electrical work for lighting, refrigerators, and outlets, ensuring your space is safe and convenient to use after dark. It also covers the plumbing needed for a sink and ice maker, providing the convenience of running water for food prep and cleanup. A professional team can handle all the behind-the-scenes work to ensure your gas lines, wiring, and pipes are installed correctly and up to code, giving you a safe, complete, and ready-to-use outdoor kitchen.
Breaking Down the Cost of an Outdoor Kitchen
Before you can figure out financing, you need a realistic budget. The cost of an outdoor kitchen on Long Island varies quite a bit, depending on the size, appliances, and materials you choose. Think of it like building any room in your house; you can go for simple and functional or all-out luxury. Understanding these different budget tiers will help you decide what features are most important to you and what kind of financing will best fit your project. Let’s look at what you can generally expect at different price points.
Entry-Level Kitchen Costs
For a budget between $15,000 and $25,000, you can build a beautiful and functional entry-level outdoor kitchen. This price range typically covers the essentials for a great outdoor cooking setup. You can expect a high-quality built-in grill, durable countertops, and enough cabinet space for your tools. While the layout might be more compact, it’s the perfect way to get started with alfresco dining. This option provides all the core components you need to start grilling and entertaining in your backyard without an overwhelming initial investment.
Mid-Range Kitchen Costs
If your budget is in the $25,000 to $50,000 range, you can really start to personalize your space. This tier allows for more flexibility in both design and features. You can incorporate upgraded appliances like an outdoor refrigerator, a sink, or side burners. It also opens the door to higher-end materials for your countertops and patio, such as beautiful and resilient porcelain and natural stone. This price point strikes a wonderful balance, giving you a more customized and luxurious kitchen that feels perfectly integrated with your home and lifestyle.
High-End Custom Kitchen Costs
For those dreaming of the ultimate outdoor culinary oasis, a high-end kitchen typically starts at $50,000 and can go up from there. At this level, the possibilities are nearly endless. Think premium, commercial-grade appliances, a pizza oven, a smoker, extensive bar seating, and a full sink with hot and cold water. The design can feature intricate custom masonry and be fully integrated under a pavilion for a complete outdoor living room experience. This is for the homeowner who wants a truly bespoke entertainment hub that will be the centerpiece of their backyard for years to come.
What Are Your Financing Options?
An outdoor kitchen is a fantastic investment in your home and lifestyle, but you don’t have to pay for it all at once. Financing can make your dream project a reality sooner, allowing you to spread the cost over time. The right financing plan helps you manage your budget without draining your savings, so you can get the high-end appliances and beautiful finishes you really want. Think of it as a tool to build your perfect outdoor space without compromise.
There are several paths you can take, each with its own set of benefits. You can work directly with your contractor on a payment plan, take out a loan specifically for home improvements, or leverage the equity you’ve already built in your home. Some homeowners even use credit cards for smaller-scale projects or to cover specific purchases. At Gappsi, we can help you explore the options that make the most sense for your project scope and financial situation. Understanding these choices is the first step toward firing up the grill in your brand new outdoor kitchen.
Contractor Payment Plans
One of the most straightforward ways to finance your project is through a payment plan offered directly by your contractor. Many reputable Long Island companies, including Gappsi, provide in-house financing options to make the process as smooth as possible. This is a great choice because it keeps everything under one roof. You work with one team for the design, construction, and payment.
These plans are often flexible and tailored specifically for home renovation projects. Instead of seeking a loan from a third party, you can arrange a payment schedule that aligns with your project’s milestones. It simplifies the paperwork and lets you focus on the exciting parts, like choosing your porcelain countertops and appliances.
Home Improvement Loans
A home improvement loan is a type of personal loan created specifically for projects like building an outdoor kitchen. These are typically unsecured loans, which means you don’t have to use your home as collateral. Lenders specialize in connecting homeowners with flexible financing that makes it easy to fund your entire project, from the grill to the stonework.
Because these loans are designed for renovations, the application process is often quick and you can get your funds in a lump sum. This allows you to pay your contractor and purchase materials without delay. It’s an excellent option if you want to keep your home’s equity separate or if you prefer a simple, fixed-term loan with predictable monthly payments.
Home Equity Loans and HELOCs
If you’ve built up equity in your home, you can use it to finance your outdoor kitchen. You have two main options: a home equity loan or a home equity line of credit (HELOC). A home equity loan gives you a lump sum of cash with a fixed interest rate, which is great for a project with a clearly defined budget. A HELOC, on the other hand, works more like a credit card, giving you a revolving line of credit you can draw from as needed.
This flexibility is perfect for larger projects that might evolve, like adding a pavilion or new landscaping alongside your kitchen. Since these loans are secured by your home, they often come with lower interest rates than unsecured personal loans.
Credit Card Financing
Using a credit card to finance your outdoor kitchen can be a smart move, especially for smaller projects or for covering specific costs like appliances or furniture. If you have a card with a low or 0% introductory APR, you could potentially finance your purchases interest-free if you pay the balance off before the promotional period ends. This method offers maximum convenience and is ideal for homeowners who don’t want to go through a formal loan application process.
However, it’s important to be mindful of high standard interest rates. This option works best if you have a solid plan to pay off the balance quickly. It’s a great tool for managing discrete expenses within your larger project budget without committing to a long-term loan.
Should You Finance or Pay in Full?
Deciding how to pay for your new outdoor kitchen is one of the most important choices you’ll make. It’s not just about whether you have the cash on hand; it’s a strategic decision that affects your personal finances and the scope of your project. Financing can make a high-end project more accessible by breaking it down into predictable monthly payments, while paying in full means you avoid interest and own your new space outright from day one.
There’s no single right answer. The best path forward depends on your financial comfort level, your project’s total cost, and your long-term goals. Maybe you want to preserve your savings for other investments or emergencies. Or perhaps you’d rather get the project done without a lingering monthly payment. By weighing the benefits of each approach, you can feel confident in your choice and focus on what really matters: creating an outdoor kitchen you’ll love for years to come. We’ll walk through the key considerations to help you decide what makes the most sense for you and your family.
Preserve Your Cash Flow
One of the biggest advantages of financing is that it allows you to keep your cash in the bank. A major home improvement project is a significant expense, and paying for it all at once can deplete your savings. By opting for a payment plan, you can hold onto your cash for emergencies, other investments, or simply for peace of mind.
Financing transforms a large, intimidating lump sum into a series of manageable monthly payments that fit into your existing budget. This makes it easier to move forward with the home remodeling project you’ve been dreaming of without putting a strain on your finances. It gives you financial flexibility and control, ensuring your outdoor kitchen is a source of joy, not stress.
Get Higher-Quality Materials and Appliances
Financing can empower you to build the outdoor kitchen you truly want, not just the one you can afford to pay for in cash today. It expands your budget, giving you the freedom to invest in higher-quality materials and premium appliances. Instead of settling for less, you can select the durable natural stone countertops, top-of-the-line grill, and beautiful masonry that will stand the test of time.
This isn’t about overspending; it’s about investing in quality that pays off in the long run. Better materials and appliances not only look more impressive but also offer superior performance and longevity, reducing the need for future repairs or replacements. With a flexible payment plan, your dream design is within reach.
Capitalize on Seasonal Promotions
Timing is everything, and having financing secured means you can act quickly when a great opportunity arises. Throughout the year, Gappsi and our suppliers may run special offers, seasonal discounts, or promotions on everything from grills to stone pavers. If you’re waiting to save up the full amount in cash, you might miss out on these limited-time deals.
With a financing plan in place, you’re ready to commit when the price is right. Gappsi often has special offers or financing plans available to help you bring your vision to life without delay. This allows you to take advantage of the best value and get your project started sooner, ensuring you can enjoy your new outdoor kitchen during the perfect season.
When Paying in Full Is the Better Choice
While financing is a great tool, sometimes paying in full is the most straightforward and cost-effective option. The most obvious benefit is that you avoid paying interest. Over time, interest charges can add a considerable amount to your project’s total cost, so paying with cash means the price you see is the price you pay. You’ll own your outdoor kitchen outright from the moment it’s finished, with no monthly payments to think about.
If you have enough savings to cover the project without compromising your financial security, paying in full can be a smart move. It’s a clean transaction that simplifies your finances. Don’t assume financing is a must for every big project; if paying cash fits comfortably within your budget, it’s an excellent and often preferred choice.
How to Choose the Right Financing Plan
Once you have a few financing options on the table, it’s time to compare them. Finding the right plan isn’t just about securing the funds; it’s about finding a solution that fits comfortably within your budget for the long haul. The details matter, from the interest rate to the fine print. Taking the time to understand each component of a loan offer will help you make a confident choice, ensuring your beautiful new outdoor kitchen brings you joy, not financial stress. Let’s walk through the key factors you should look at when comparing financing plans.
Interest Rates and APR
The first thing most people look at is the interest rate, but it’s the Annual Percentage Rate (APR) that gives you the full picture. The APR includes the interest rate plus any lender fees, giving you a more accurate measure of the loan’s total cost. A lower APR means you’ll pay less over the life of the loan, so it’s a critical number to compare. Some lenders offer financing specifically for large-scale home improvement projects, which can be a great fit for a custom outdoor kitchen. When you compare loan offers, always use the APR as your main point of comparison to see which deal is truly the best.
Repayment Terms and Monthly Payments
Your repayment term is the amount of time you have to pay back the loan. Lenders often offer a range of terms, sometimes extending up to 20 years for larger projects. A longer term will result in lower monthly payments, which can make a big project feel more manageable. However, keep in mind that a longer term usually means you’ll pay more in total interest over time. It’s a trade-off between a comfortable monthly payment and the overall cost of borrowing. Use a loan calculator to play with different terms and see how they affect both your monthly payment and the total interest you’d pay.
Down Payment Requirements
Some financing plans require you to pay a portion of the project cost upfront, which is known as a down payment. For many homeowners, coming up with a large down payment can be a significant hurdle. The good news is that many modern financing options, especially those designed for home improvements, don’t require a hefty down payment. Some loans don’t even require you to have equity in your home to qualify. This makes it much easier to get your project started without draining your savings. When exploring options, be sure to ask about down payment assistance or no-down-payment loans if a large initial outlay is a concern for you.
Hidden Fees and Penalties
A loan offer might look great on the surface, but hidden fees can quickly change the math. Always read the fine print and ask about any costs that aren’t immediately obvious. Look for things like origination fees (for processing the loan), application fees, or prepayment penalties, which charge you for paying off the loan early. A trustworthy lender will be transparent about all associated costs. Don’t be afraid to ask for a complete breakdown of every fee before you sign anything. Understanding these potential loan agreement pitfalls is key to avoiding unpleasant surprises down the road.
Flexibility and Payment Options
Life happens, and having a financing plan with some flexibility can make a huge difference. Some lenders and contractors offer flexible payment plans that can help you manage your budget more effectively. This could include the ability to make extra payments without a penalty or options to adjust your payment date. When you discuss your project with a company, ask about the payment options they support. At Gappsi, we work with our clients to create stunning outdoor living spaces and believe the process should be as smooth as possible. We can help you understand what to expect and guide you toward a solution that works for your family.
Where to Find Outdoor Kitchen Financing on Long Island
Once you have a clear vision and a budget for your outdoor kitchen, the next step is securing the funds. Finding the right financing partner is just as important as choosing the right materials. For homeowners on Long Island, there are several excellent avenues to explore, each with its own set of benefits. You can work directly with a full-service company that offers its own financing, turn to a familiar local bank, or connect with a lender that specializes in home improvement projects. The best path for you depends on your financial situation, project scope, and personal preferences. Let’s look at some of the most common places to find outdoor kitchen financing in our area.
Gappsi
Working directly with your design and build team for financing can make the entire process feel seamless. At Gappsi, we believe that financial hurdles shouldn’t stand between you and your dream outdoor living space. We offer tailored financing options to help make your project a reality. By handling everything in-house, from the initial design to the final installation and financing, we streamline communication and simplify your project management. Our team can walk you through our available plans to find one that fits your budget, helping you get started without the stress of a large upfront payment. This integrated approach allows you to focus on the exciting parts, like choosing your outdoor appliances and finishes.
Local Banks and Credit Unions
Your local bank or credit union can be a fantastic resource for financing your outdoor kitchen. Since you likely already have a relationship with them, the application process might be more straightforward. Long Island banks and credit unions have a deep understanding of the local real estate market and recognize the value that a high-quality outdoor kitchen adds to your home. They often provide home improvement loans with competitive interest rates and personalized customer service. Don’t hesitate to schedule a meeting with your local branch to discuss your project. They can present you with options that might be a perfect fit for your financial goals and help you achieve your dream project.
Third-Party Home Improvement Lenders
Another popular route is working with a third-party lender that specializes in home improvement loans. Companies like HFS Financial focus exclusively on connecting homeowners with financing for projects just like yours. These lenders often provide flexible outdoor kitchen loans that don’t require you to tap into your home’s equity. Many offer features like staged funding, where funds are released as your project hits certain milestones, which helps you manage your budget effectively. Some contractors have partnerships with these lenders, making the process even easier. Exploring these specialized options can help you find competitive rates and terms designed specifically for home renovation projects.
Tips for Getting the Best Financing Deal
Securing the right financing for your outdoor kitchen is a huge step, and with a little preparation, you can find a deal that makes you feel confident and excited. Think of it like this: you wouldn’t choose your countertops without seeing a few samples, right? The same principle applies to loans. Taking the time to understand your options and ask the right questions will help you save money and avoid surprises down the road. These tips will guide you through the process so you can focus on what really matters, like planning your first backyard barbecue.
Know Your Credit Score
Before you start applying for loans, it’s a good idea to know where you stand with your credit. Your credit score is a key factor lenders use to determine your interest rate and loan terms. While you generally need a good credit score to get the most competitive offers, you don’t need a perfect one. Many financing solutions are available for a range of credit profiles. You can check your score for free through many credit card companies or credit monitoring services. Knowing your number ahead of time gives you a realistic picture of what to expect and puts you in a better position to negotiate.
Compare Multiple Offers
Don’t feel pressured to accept the very first financing offer you receive. Even with rising construction costs, it’s still possible to finance and own the home of your dreams without overextending your budget. We recommend getting quotes from at least three different sources. You can explore options through your contractor, your local Long Island bank or credit union, and third-party home improvement lenders. Laying all the offers out side-by-side allows you to compare interest rates, repayment terms, and fees. This simple step ensures you’re getting a truly competitive deal that works for your family and your financial goals.
Ask About Promotions and Negotiate
It never hurts to ask about a discount. Many contractors and suppliers have seasonal deals or preferred lending partners that can save you money. At Gappsi, we often have special offers or unique financing plans available to help you build your ideal outdoor kitchen. When you’re reviewing a financing agreement, don’t be afraid to ask questions or see if there’s any room for negotiation on the terms. The worst they can say is no, and you might be surprised at what you can achieve just by speaking up and expressing your needs.
Look Out for Hidden Fees
One of the biggest budgeting mistakes homeowners make is underestimating the project’s total scope. The initial quote for your appliances and counters might not include everything. Be aware of potential hidden costs like site preparation, extending gas and electrical lines, or adding plumbing for a sink. To avoid any surprises, ask your contractor for a detailed, itemized proposal that clearly outlines what is and is not included in the price. A transparent partner will be happy to walk you through every line item, ensuring you have a complete and accurate budget from the start.
Budget for Permits and Extras
Beyond the main construction, there are a few other costs to factor into your budget. Most outdoor kitchen projects require building permits from your local town, and the fees can vary across Long Island. It’s also wise to set aside a small contingency fund, maybe 10% of the total cost, for any extras or unexpected changes you might want to make along the way. The good news is that you can often bundle nearly all of your home remodeling projects and associated costs, including permits, into one straightforward financing plan. This simplifies your payments and prevents you from having to cover last-minute expenses out of pocket.
Start Planning Your Outdoor Kitchen Today
Turning your dream of an outdoor kitchen into a reality is an exciting process, and it’s more achievable than you might think. For many Long Island homeowners, the main question isn’t about design or features, it’s about the budget. The great news is that you don’t have to wait years to save up for the full cost. Flexible financing options are designed to help you get your project started sooner, allowing you to enjoy your new space without draining your savings. By exploring these payment solutions, you can move from dreaming to doing.
Many homeowners find success by working directly with their contractor to find a suitable payment plan. At Gappsi, we can guide you through the financing process to find a solution that fits your financial situation. We believe that building your perfect outdoor living area should be a smooth and manageable experience. When you partner with us for your home remodeling project, we can help you understand the costs and explore ways to make your investment comfortable for your budget.
If you prefer to secure funding independently, you can also look into specialized home improvement loans. Companies like HFS Financial focus specifically on connecting homeowners with outdoor kitchen loans, often with flexible terms and no home equity requirements. Taking the time to explore these different avenues gives you the power to choose the best path forward. With the right financing in place, you can confidently invest in the high-quality materials and appliances that will make your outdoor kitchen last for years to come.
Related Articles
- Hiring an Outdoor Kitchen Contractor on Long Island
- Your Guide to Outdoor Kitchen Designers on Long Island
- Amazing Outdoor Kitchens Long Island – Gappsi Group
- Outdoor Kitchen Contractor Long Island: A Hiring Guide
- Outdoor Kitchen Design & Installation in Long Island | Gappsi Inc
Frequently Asked Questions
Do I need a perfect credit score to finance an outdoor kitchen? Not at all. While a higher credit score generally helps you secure the best interest rates, you don’t need a perfect score to qualify for financing. Many lenders, especially those specializing in home improvement loans, have programs designed for a wide range of credit profiles. The most important step you can take is to know your score before you start applying. This gives you a realistic idea of what to expect and puts you in a stronger position when discussing your options.
How long does it typically take to get approved for financing? The timeline can vary depending on the path you choose. Financing directly through a contractor like Gappsi or a third-party lender like HFS Financial is often the fastest route, with approvals sometimes happening in just a few days. This speed allows you to move forward with your project quickly. If you opt for a home equity loan or HELOC from a bank, the process might take a bit longer, usually a few weeks, as it involves more detailed paperwork and an appraisal of your home.
Can I finance just a portion of my project, like the appliances or the masonry? Absolutely. Financing is flexible, and you don’t have to finance the entire project. Many homeowners use it as a tool to bridge the gap between their savings and the total cost. For example, you might pay for the masonry work with cash and then finance the high-end appliances and pavilion. This hybrid approach allows you to get the exact features you want without depleting all of your savings, giving you control over your budget.
Is it better to get financing through my contractor or a bank? There isn’t a single “better” option, as it really depends on your priorities. Getting financing through your contractor is often the most convenient choice. It streamlines the process by keeping your design, build, and payments all with one team. On the other hand, approaching your own bank or credit union, where you have an existing relationship, might get you a very competitive rate. The best strategy is to explore both options to see which plan offers the terms and simplicity that feel right for you.
Will financing my outdoor kitchen affect my ability to get other loans in the future? This is a smart question to ask. Taking on any new loan can have a temporary effect on your credit score, and it will be factored into your debt-to-income ratio. However, as long as you make your payments consistently and on time, the loan can actually help build a positive credit history over the long run. Lenders see a history of responsible payments as a good thing. As long as the monthly payment fits comfortably within your budget, it shouldn’t prevent you from securing other loans when you need them.